








⚖️ Disclaimer: Credit card terms, APRs, and eligibility requirements change frequently. The information in this guide reflects our research as of April 2026 and may not capture recent updates. Always confirm current terms directly with each card issuer before applying.
For many nonprofits, expenses still run through the executive director's personal credit card—or there’s no formal system at all. But as your organization grows, a dedicated nonprofit credit card makes expense management cleaner, separates personal and organizational finances, and often includes perks like lower (or zero!) fees and better spend controls.
We've rounded up the best nonprofit credit cards based on research and user reviews, plus what to look for before you choose. And if you're already a Givebutter user, there might be a card waiting for you inside the platform.
What to look for in a nonprofit credit card
For-profit businesses often have a credit card strategy, but it’s less common among nonprofits. Here’s what to look for when comparing nonprofit credit cards for your organization:
- Personal guarantee requirement: Some cards, typically commercial business credit cards that offer cashback or rewards, require a personal guarantee, making you personally liable for business debts. Others keep your individual and nonprofit finances separate.
- APR and fees: Annual Percentage Rates (APR) outline the total cost of borrowing, and these vary between providers. Look for cards with no annual fee and transparent late payment policies.
- Rewards structure: Some credit cards offer points-based reward programs, cashback earnings, or nonprofit-specific discounts. Match the rewards structure to how your org actually spends.
- Spending controls and reporting features: Business and nonprofit credit cards typically include robust controls and reporting to help you manage spending in line with your strategies and policies.
- Nonprofit-specific perks: Higher card limits and reduced fees are common benefits for nonprofit organizations.
6 nonprofit credit cards & alternatives at a glance
1. Givebutter Wallet Spend Card: Best for faster access to settled funds
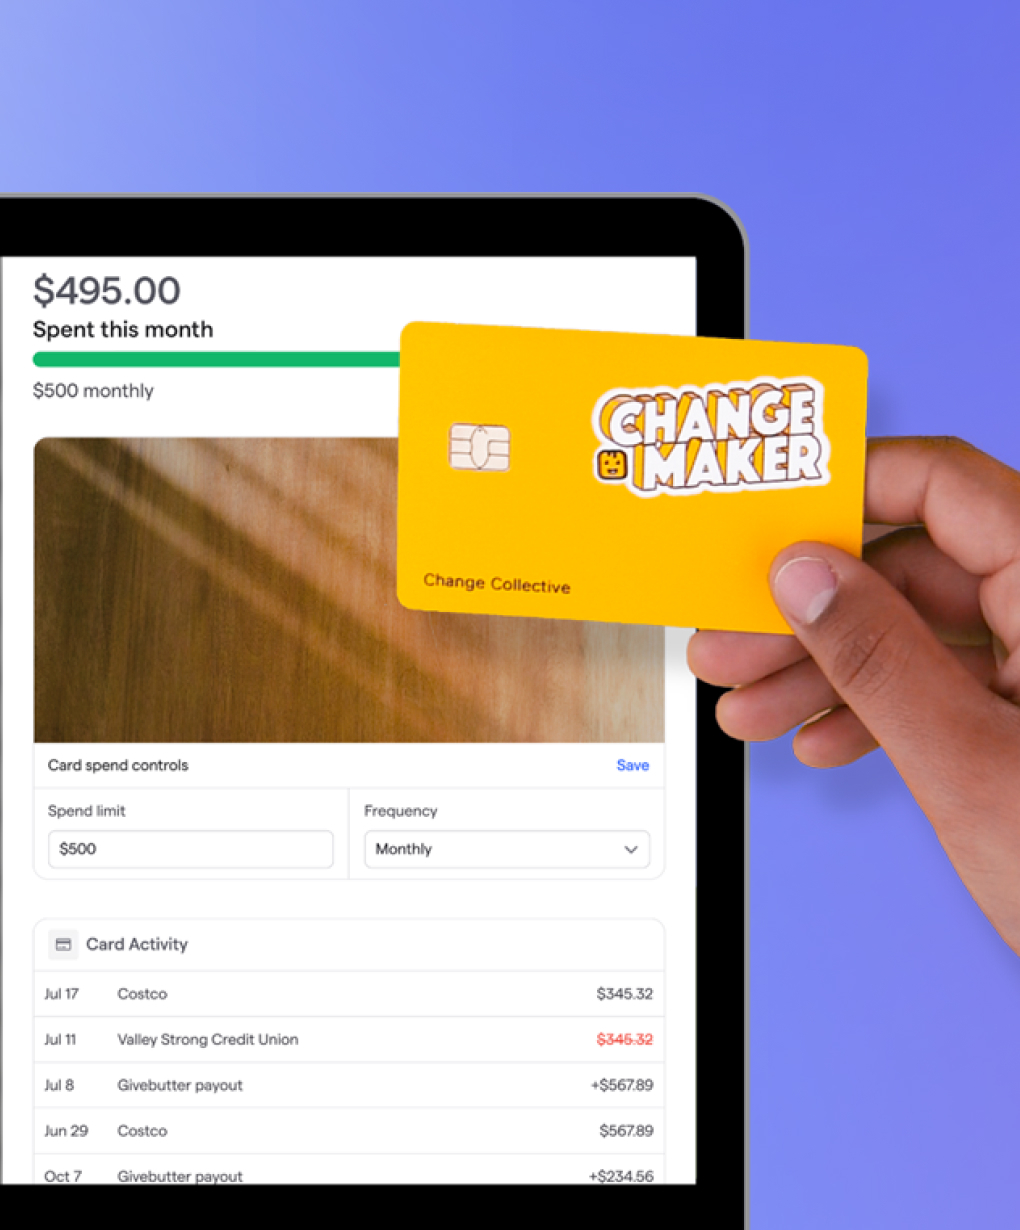
Givebutter Wallet Spend Cards connect fundraising and spending in one place. An alternative to credit cards, these virtual and physical Visa cards let you pay directly from your available Wallet balance—without borrowing or transferring funds to an external bank account.
📣 Standout features:
- Virtual or physical Spend Cards
- Faster access to settled funds
- Per-card spending limits and freeze/unfreeze controls
- Automatic transaction logging
💰 Fees: No annual fee
✔️ Eligibility: Requires an active Givebutter Wallet with onboarding completed. Admin and Finance users can create cards for themselves after confirming their cardholder information and accepting the cardholder Terms of Service.
✅ Best for: Nonprofits that want to put their Givebutter funds into action faster
🔥 Our take: Givebutter is the first and only fundraising platform with embedded spending tools, giving nonprofits a more efficient, built-in solution to manage and spend funds. Spend directly from available Wallet funds without transferring them to an external bank account, with card activity tracked in your Givebutter dashboard.

Earn APY rewards on every dollar raised
2. CharityCharge: Best for dedicated nonprofit credit lines
CharityCharge is the only traditional credit card designed specifically for nonprofits. The card offers clear visibility into spending and simplifies expense management.
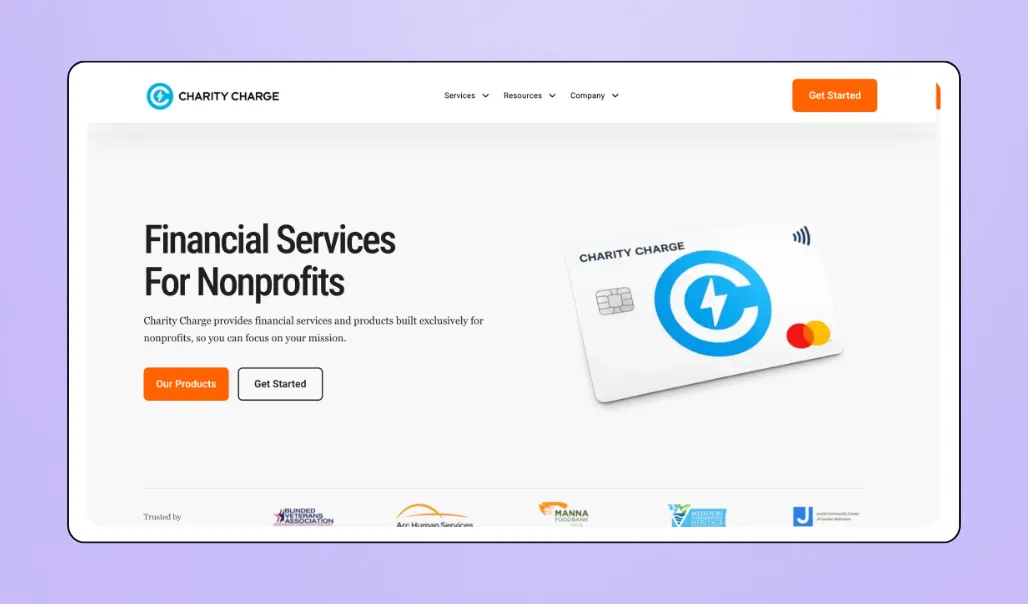
📣 Standout features:
- Virtual and physical cards
- Real-time spending controls
- Receipt capture
- Expense management
- Centralized spend management
- Syncs with accounting software like QuickBooks and Sage
💰 Fees: No annual fee; late fees may apply
✔️ Eligibility: Must have 501(c) nonprofit status and meet annual revenue requirements. Nonprofits that don’t meet the eligibility requirements may still qualify for a Secured Credit Card.
✅ Best for: Nonprofits that prefer a traditional credit card
🔥 Our take: CharityCharge’s spending visibility allows nonprofits to see what’s being spent and by whom, and tools like receipt capture and expense management simplify the administrative work behind the scenes.

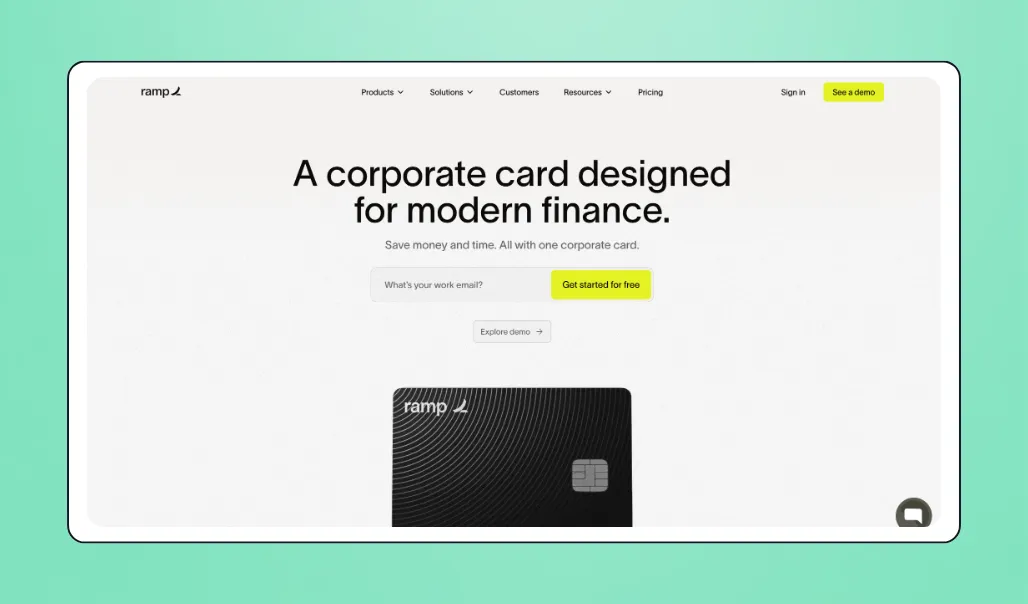
3. Ramp: Best for expense controls
Ramp’s business cards are part of its financial management platform, which allows nonprofits to track spending, capture expenses, and prepare board-level reports.
📣 Standout features:
- Transactions recorded with fund codes and expense classifications
- Real-time spend tracking
- Spending limits and freeze cards
- Uncapped cashback on every card purchase
💰 Fees: No annual fee
✔️ Eligibility: Must be registered in the U.S. as a corporation, LLC, or partnership, with at least $25K in a business bank account. Organizations also need a physical address in the U.S. and operate primarily within the country.
✅ Best for: Nonprofits looking for robust expense controls
🔥 Our take: Ramp is popular with nonprofit changemakers for its ability to track spend by fund code or budget, and controls that allow for smoother decision-making for program leads. It’s also an option for nonprofits that are looking for a complete financial management platform, not just a standalone credit card.
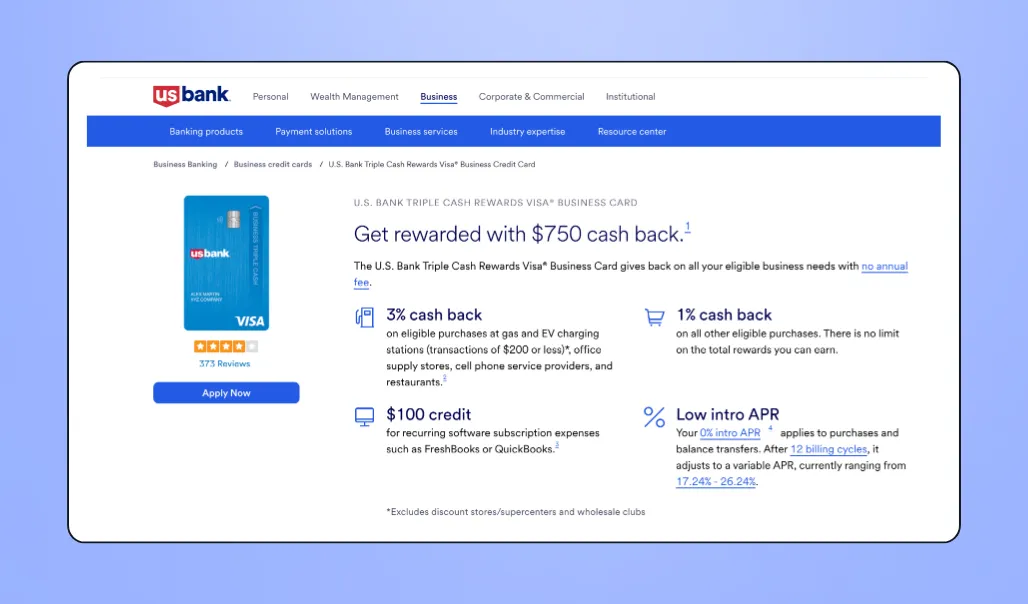
4. U.S. Bank Triple Cash Rewards Visa® Business Card: Best for cashback rewards
U.S. Bank offers several business credit cards, but this one is ideal for nonprofits looking to stretch their funds with cashback rewards.
📣 Standout features:
- Online account management
- Expense management
- Free employee credit cards
- Cash flow tool
- Up to 3% cash back on eligible purchases
- $100 credit towards eligible recurring software subscription expenses
💰 Fees: No annual fee; late payment fees apply
✔️ Eligibility: Open to businesses and nonprofit organizations
✅ Best for: Nonprofits that can maximize cashback rewards
🔥 Our take: This U.S. Bank credit card is a solid option for organizations that spend heavily in categories eligible for the 3% cashback offer. Best suited for organizations with strong credit scores.
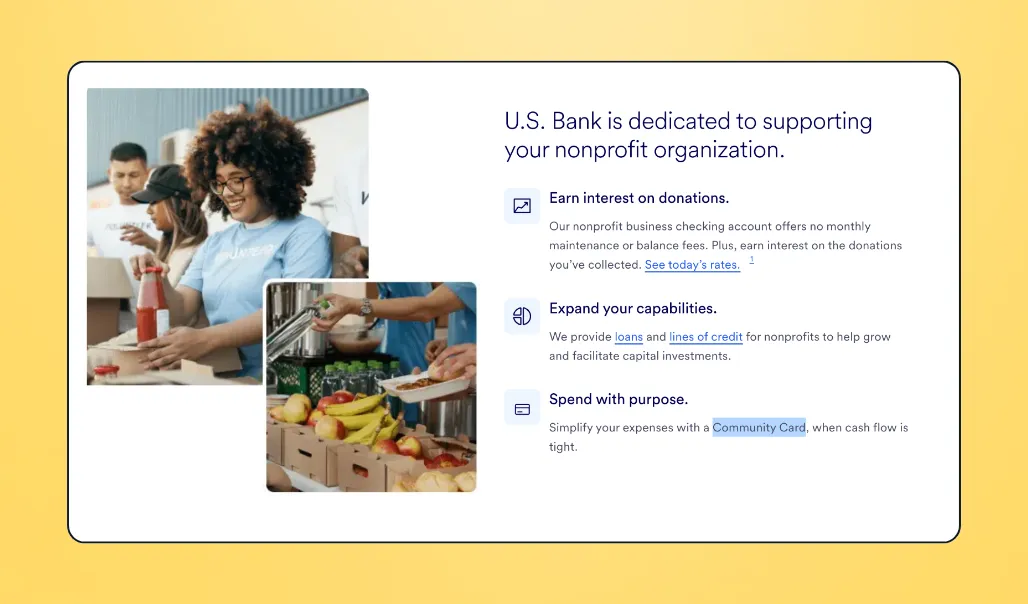
5. U.S. Bank Community Card: Best for simple, traditional banking
U.S. Bank also offers a specialized credit card program for nonprofits, the Community Card, available in both standard and rewards-specific versions.
📣 Standout features:
- Online account management
- Expense management
- Employee cards
- Cash flow tool
- Designed especially for nonprofit organizations
- Optional rewards, including 1% cash back
💰 Fees: No annual fee
✔️ Eligibility: Must be a 501(c)(3) or 501(c)(4) nonprofit organization
✅ Best for: Nonprofits wanting a familiar banking partner with simple financial management tools
🔥 Our take: U.S. Bank is a trusted name in nonprofit finance, and its credit card options are ideal for organizations that already use U.S. Bank or that may not qualify for more restrictive options.
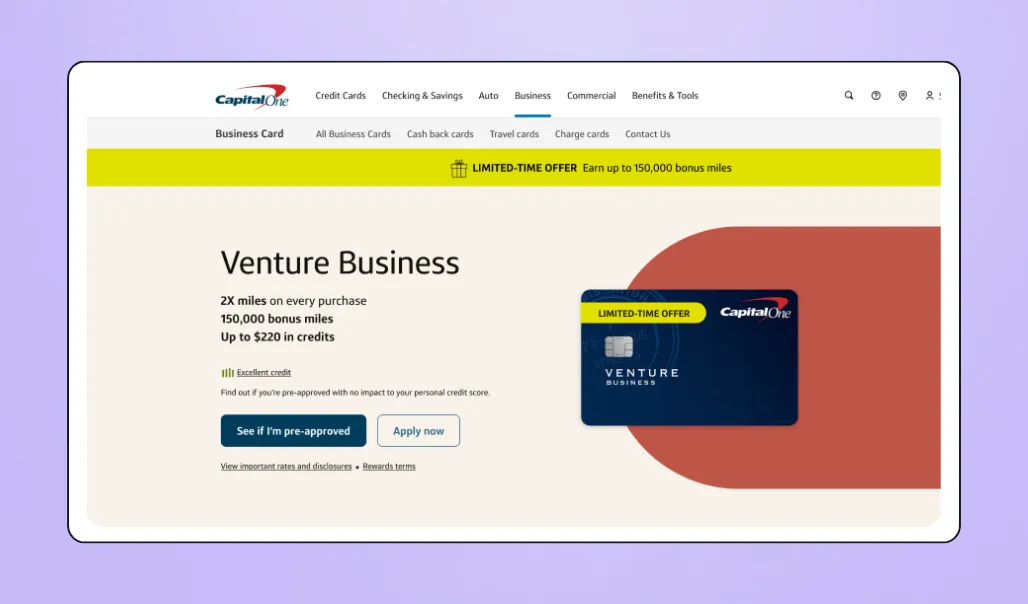
6. Capital One Venture Business: Best for travel rewards
This business credit card offers 2X miles on every purchase and a generous 150,000-mile welcome bonus, making it a popular choice for nonprofit leaders who travel frequently.
📣 Standout features:
- Physical and virtual cards
- Purchase records
- Free employee cards
- Expense management
- Spend limits and account managers
💰 Fees: $95 annual fee; late fees apply
✔️ Eligibility: Open to businesses and nonprofit organizations. Requires an excellent credit score.
✅ Best for: Nonprofits that can make the most of bonus miles and travel rewards
🔥 Our take: For organizations with frequent travelers, a card like this can help maximize the mileage benefits. Like many rewards cards, it’ll require an excellent credit rating.

Close the loop between raising & spending with Givebutter
Choosing the right credit card can simplify how your nonprofit spends, tracks, and maximizes funds. Whichever card you choose, pairing it with a free fundraising platform means more of every dollar raised stays with your mission. And if you want to close the loop between raising and spending fully, Givebutter now makes that possible.
Most platforms stop at “transfer funds to your bank account.” Givebutter goes further. With Givebutter Wallet, settled donations land in a financial home base where funds earn APY rewards while they sit. And with Wallet Spend Cards, your team gets faster access to settled funds through virtual or physical Visa cards, with built-in spending controls, per-card limits, and automatic transaction logging.
Sign up for Givebutter for free and see why nonprofits use it for more than just fundraising.
FAQs about credit cards for nonprofits
Can I get a credit card for my nonprofit organization?
Yes, most nonprofits can qualify for a business credit card. It’s often a strategic part of nonprofit accounting and offers benefits like accounting clarity and a robust audit trail. Choosing the right card depends on your organization’s structure, needs, and whether you want to avoid personal liability.
Do nonprofits need a personal guarantee for a credit card?
Some nonprofit credit cards require a personal guarantee, but others don’t. A personal guarantee creates financial liability for individuals—something that most nonprofit leaders want to avoid.
Givebutter Wallet Spend Cards offer an alternative to borrowing: They draw directly from your available Wallet balance, so you can only spend funds you already have.
What is the best credit card for a nonprofit?
If you’re already using Givebutter, Wallet Spend Cards are a strong alternative to traditional credit cards. For nonprofit-specific perks, CharityCharge is a popular choice. For strong expense controls, Ramp stands out. And for cashback or travel rewards, consider U.S. Bank or Capital One.
Can a 501(c)(3) have a business credit card?
Yes, 501(c)(3) organizations can and should have their own credit cards rather than relying on personal credit cards, which can cause liability, audit, and record-keeping issues. A business credit card for nonprofits keeps finances separate, makes expense tracking easier, and supports effective financial stewardship.
Share this article